When your static caravan insurance renewal arrives, it’s natural to look at the price first. With pitch fees, maintenance and everyday bills to consider, every saving counts.
But how do you know whether a cheaper quote offers the cover you need?
The best starting point is to compare the details alongside the price. Here are the main things to check before choosing insurance for your static caravan or holiday lodge.
Start with the same information
To make a useful comparison, give each provider the same details about your holiday home, its value, location and use.
Explain whether you use it yourself, lend it to family and friends, or let it to paying guests. Ask each provider to confirm that the proposed policy accommodates your arrangements.
Keep your existing schedule and renewal invitation handy. These make it easier to spot differences between your current insurance and a new quote.
Check new-for-old or market-value cover
This is one of the most important differences to understand.
New-for-old cover generally bases replacement on a new equivalent holiday home, subject to the policy’s eligibility rules and settlement conditions.
Market-value cover generally bases settlement on what your holiday home was worth immediately before the loss, taking account of its age and condition.
Check any age restrictions and what happens if you decide not to replace the caravan. A new-for-old policy may have different terms for a cash settlement.
Two quotes on different replacement bases are not a like-for-like comparison.
Make sure the insured values are right
Don’t simply carry forward last year’s figures without reviewing them.
For new-for-old cover, check the current cost of a suitable new equivalent. Your original purchase price may not be the appropriate figure, particularly if it included items beyond the holiday home itself.
Review contents too. Furniture, televisions, kitchen equipment, bedding and other belongings can add up.
If you’re unsure which costs belong in which section, ask the provider to explain before accepting the quote.
Compare the excesses
The excess is the amount you contribute towards a claim.
Look beyond the standard excess and check whether different amounts apply to particular claims, such as storm or escape of water. Also check whether a voluntary excess has been added.
For example, a £30 saving on the annual premium may look less attractive if the excess for a claim you’re concerned about is £200 higher. That doesn’t automatically make the policy unsuitable, but it is a difference worth understanding.
Read the winter conditions
Holiday homes are often left empty between visits, so winter and unoccupied conditions deserve careful attention.
Check:
- How the policy defines “unoccupied”.
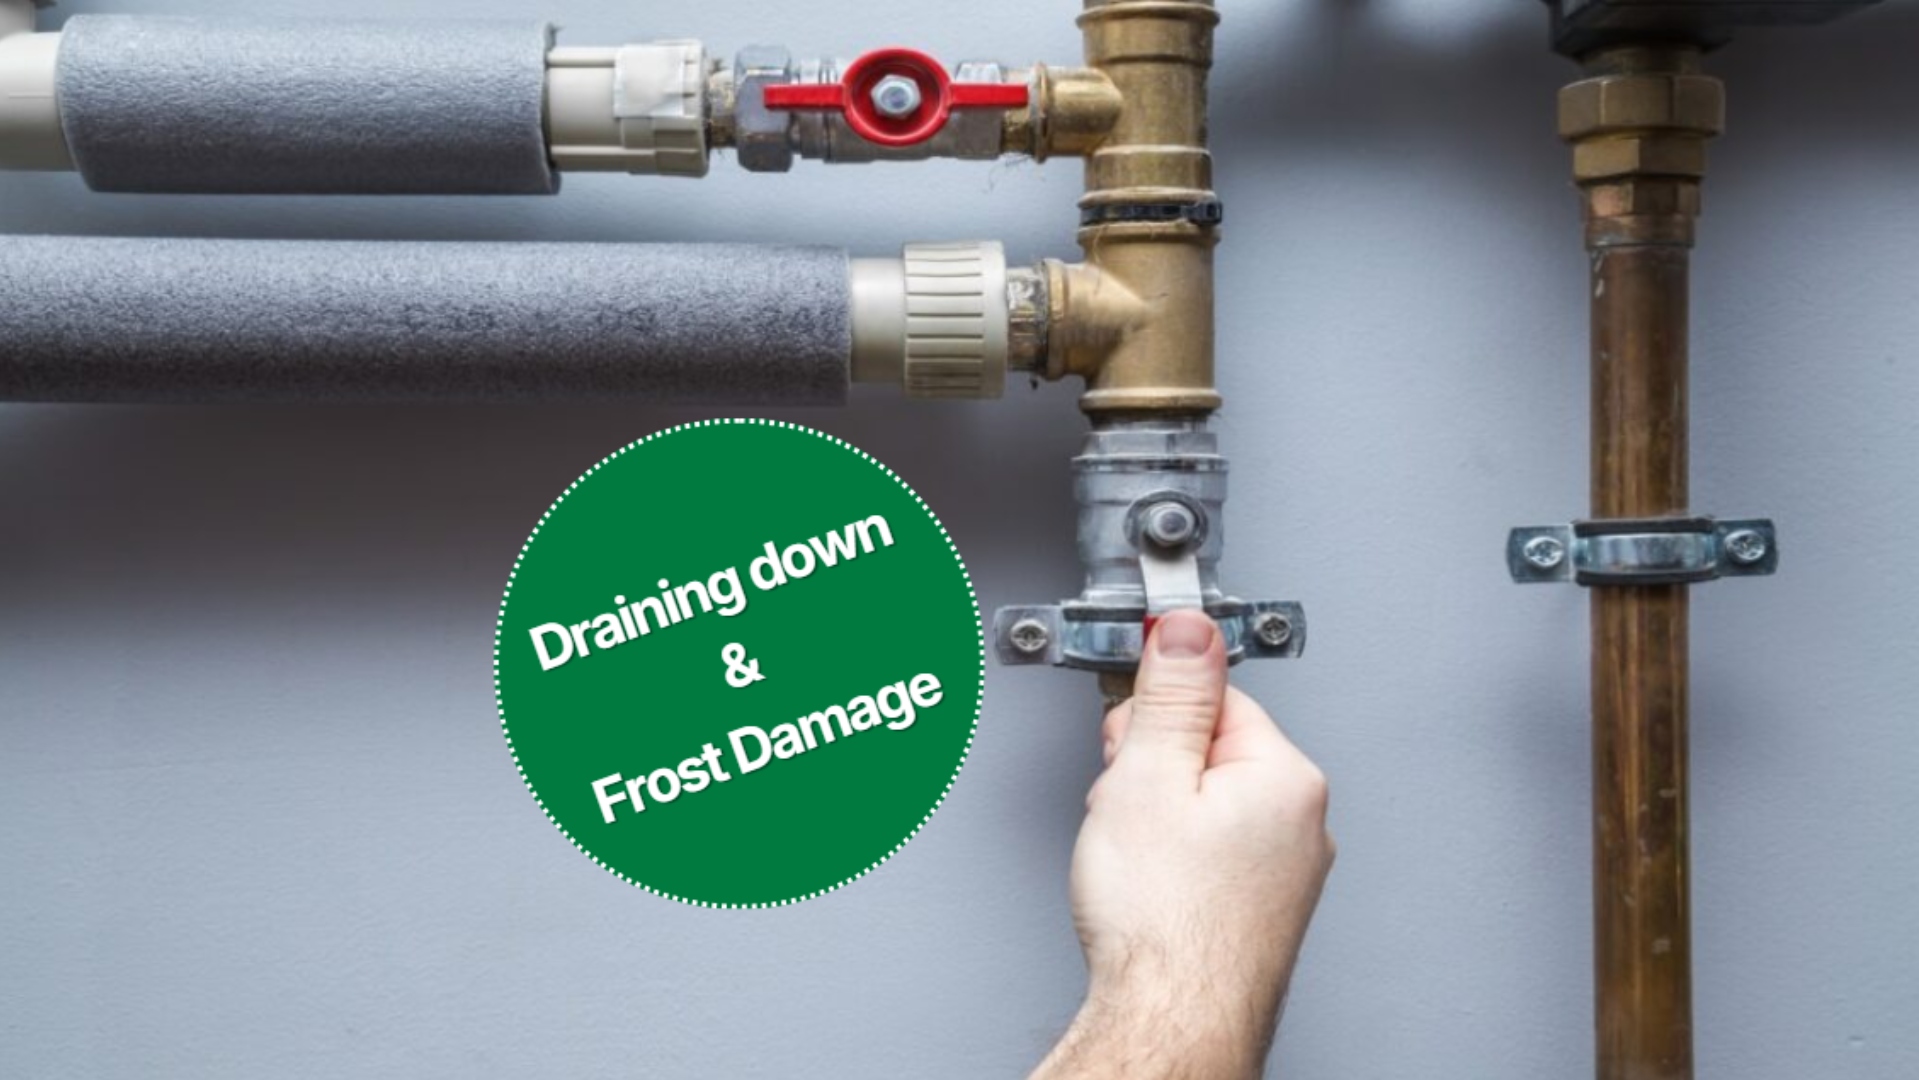
- When drain-down or other precautions are required.
- Whether you can carry out the work yourself.
- Whether heating is an accepted alternative, and under what conditions.
- What happens to cover if the requirements aren’t followed.
Don’t assume the insurance conditions follow your park’s opening season. Read the actual wording and ask about anything unclear.
Look at the costs beyond replacing the caravan
Following a serious loss, replacing the holiday home may only be part of the expense.
There can also be costs for removing debris, delivering a replacement, re-siting it and reconnecting services.
Ask whether these costs are included within the main sum insured or covered by a separate allowance. Check the limit and what it includes.
Check the cover that matters to you
Use your own holiday home as the starting point. If you have decking, a shed or expensive contents, ask how they are covered.
Questions worth putting to each provider include:
- Is accidental damage included?
- What cover applies to decking and other outside structures?
- Is vermin damage covered, and is there a separate limit?
- What limits apply to individual contents items?
- Is there cover for alternative accommodation or lost rental income?
- Does the public liability limit meet your park’s requirements?
Read exclusions as well as benefits. Insurance does not cover every problem: the NACO wording, for example, contains exclusions concerning gradual deterioration and wear and tear. An insured event and a maintenance issue can require very different responses.
Consider the service behind the policy
Price and cover matter, but so does knowing who you’ll speak to when you need help.
Check how you contact the provider, how claims are reported and what support is available. Independent reviews can help, especially those describing customers’ experiences when something went wrong.
Your quick comparison checklist
Before accepting a quote, put these details side by side:
| What to compare | |
| Total cost | Annual premium, fees and any cost of paying monthly |
| Replacement basis | New for old or market value |
| Insured amounts | Holiday home, contents and other structures |
| Excesses | Standard, claim-specific and voluntary amounts |
| Winter conditions | Unoccupied definition and required precautions |
| Additional costs | Debris removal, delivery and re-siting allowances |
| Liability | Cover limit and park requirements |
| Your use | Personal use, lending and any letting |
| Support | Contact options and claims arrangements |
See how NACO compares
If your static caravan insurance is coming up for renewal, why not get a quote from NACO?
Our team understands caravan and lodge ownership and can explain our cover in plain English, so you can compare it with your existing policy.
Get a static caravan insurance quote or call 01255 820321.
Cover is subject to eligibility, policy terms, conditions and exclusions.